
The PPC Formulas Every Marketer Should Know: A Practical Reference Guide (2026)
 Jignesh V.
19/08/2026
20 min read
Most PPC accounts don’t fail because the strategy is wrong. They fail because nobody in the room can say, with a straight face, whether the account is actually making money. Ask five people what “good ROAS” means for a given business and you’ll get five different answers — because most of them are quoting a number they read somewhere rather than one they calculated from their own margins.
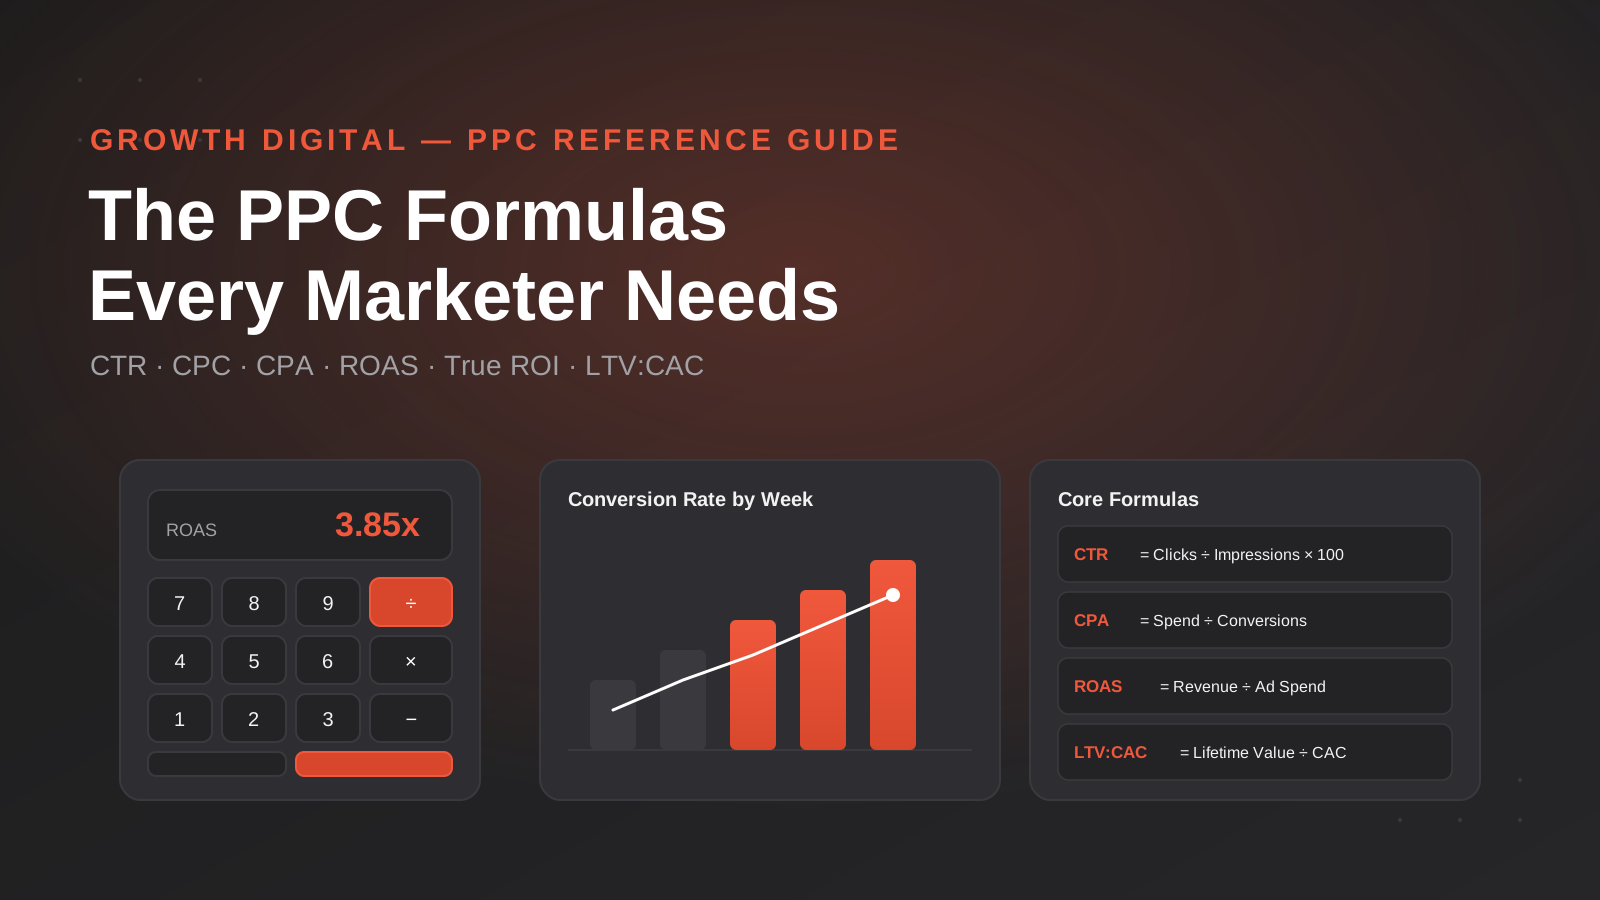
This is a reference guide, not a strategy piece. If you want the thinking behind how we structure and optimise Google Ads accounts, read our Google Ads ROI guide. This article is the opposite: no strategy, no philosophy, just the formulas — CTR, CPC, conversion rate, CPA, ROAS, true ROI, break-even ROAS, CAC, LTV:CAC, and the statistics you need to know whether an A/B test result is real. Every formula below comes with a worked example using illustrative numbers, so you can drop your own figures straight in.
We’ll build one example campaign — a fictional business we’re calling Sample Co — and carry its numbers through most of the guide, so you can see how each metric feeds the next one instead of treating them as isolated trivia. That’s the part most PPC training skips: these formulas aren’t a list of trivia to memorise, they’re a chain, and a mistake or a rounded-off assumption early in the chain distorts every number that comes after it. Bookmark this page — it’s built to be a reference you come back to mid-audit, not something you read once and forget.
Click-Through Rate (CTR)
CTR is the first metric anyone looks at, and the most commonly misread. It tells you whether your ad is relevant and compelling enough to earn a click when it’s shown — nothing more. It says nothing about whether that click converts into a customer.
The formula
CTR = (Clicks ÷ Impressions) × 100
Worked example
Sample Co’s Search campaign received 50,000 impressions and 1,250 clicks over the month.
CTR = (1,250 ÷ 50,000) × 100 = 2.5%
What counts as “good”
Benchmark CTR varies enormously by industry, match type and position, so treat any generic number with suspicion. As a rough guide, Search campaigns on branded terms often see CTR above 10–15%, while competitive non-branded terms in categories like legal or insurance can sit at 2–4% and still be considered healthy. The number only means something when you compare it against your own account’s history and your closest competitors on the same auction — not against an industry-wide average pulled from a blog post.
CTR also directly affects Quality Score, which affects CPC. A weak CTR doesn’t just mean fewer clicks — it means you pay more for the clicks you do get. That’s the first place most accounts leak money, and it’s why CTR is worth tracking even though it isn’t a profitability metric on its own.
Match type and position skew the average
A single blended CTR figure across a whole campaign hides more than it reveals, because CTR climbs sharply with ad position and tightens with match type. An exact-match keyword sitting in position one on a branded search will often post double-digit CTR, while the same account’s broad-match prospecting terms sitting in position three or four might sit under 2%. Both can be entirely healthy for what they’re doing — one is capturing demand, the other is generating it — so always segment CTR by match type and average position before comparing it against a benchmark or a previous month.
Cost Per Click (CPC)
CPC tells you what each click actually cost. It’s driven by your bid, your Quality Score, and the competitiveness of the auction at the moment your ad shows.
The formula
CPC = Total Spend ÷ Total Clicks
Worked example
Sample Co spent $6,250 to generate those 1,250 clicks.
CPC = $6,250 ÷ 1,250 = $5.00
Average CPC vs. actual CPC
Google Ads reports an “Avg. CPC” column, but that’s a blended average across every keyword, ad group and device in the campaign — it can mask serious variance. A campaign with an average CPC of $5.00 might have one ad group converting well at $3.50 a click and another burning $11.00 a click for nothing. Always drill into CPC at the ad group or keyword level before drawing conclusions from the campaign-level number. CPC in isolation isn’t good or bad — it’s only meaningful once you know what that click is worth downstream, which is where conversion rate and CPA come in.
Why CPC moves even when your bids don’t
Plenty of account managers get a fright when CPC jumps 20–30% in a month without a single bid change on their end. That’s normal, and it’s driven by the auction, not your account: a competitor increasing their budget, a seasonal spike in demand (school holidays, EOFY, Christmas), or a shift in your own Quality Score can all move CPC independently of anything you did. Before troubleshooting a CPC increase as an account problem, check whether impression share and auction insights data point to increased competition instead — it changes what you should actually do about it.
Conversion Rate
Conversion rate measures how many of your clicks turn into the action you actually care about — a lead form, a purchase, a call, a booking. It’s the bridge between traffic quality and revenue.
The formula
Conversion Rate = (Conversions ÷ Clicks) × 100
Worked example
Of Sample Co’s 1,250 clicks, 75 became qualified leads.
Conversion Rate = (75 ÷ 1,250) × 100 = 6%
The trap: conversion rate without conversion quality
A campaign can have an excellent conversion rate and still be unprofitable, because “conversion” is whatever you told the platform to count. If your form fills include spam submissions, or your “lead” definition includes people who never intended to buy, your conversion rate looks healthy while your sales team quietly drowns in junk. Before you trust this number, check it against a downstream metric — lead-to-sale rate or close rate — that reflects what actually turns into revenue. We cover this gap in more depth in the ROI guide linked above; here, just flag it as the reason CPA and ROAS matter more than conversion rate on its own.
Micro-conversions vs. macro-conversions
Not every conversion should carry the same weight in your reporting. A micro-conversion — a newsletter signup, an add-to-cart, a PDF download — signals interest but not commercial intent. A macro-conversion — a completed purchase, a booked consultation, a qualified phone call — is the one tied to revenue. If your Google Ads “Conversions” column blends both together (a common default setup), your headline conversion rate will be inflated and every CPA and ROAS figure calculated from it will be wrong. Split conversion actions into primary (macro) and secondary (micro) inside the platform, and only feed primary conversions into the formulas in this guide.
Cost Per Acquisition / Cost Per Lead (CPA / CPL)
CPA (or CPL for lead-gen businesses) is where CTR, CPC and conversion rate collapse into a single number that’s actually comparable to what the business is willing to pay for a new customer or lead.
The formula
CPA = Total Spend ÷ Number of Conversions
Worked example
CPA = $6,250 ÷ 75 = $83.33
On its own, $83.33 per lead means nothing. It only becomes useful once you compare it to what a lead is worth — which depends on your close rate and average order or contract value. If Sample Co closes 40% of leads at an average order value of $250, each lead is worth $100 in revenue (0.4 × $250), which makes an $83.33 CPA tight but survivable before you’ve even accounted for margin. Run that same CPA against a 15% close rate and a $120 order value, and you’re underwater before the product is even delivered. CPA is never a target you can set in isolation — it has to be reverse-engineered from your economics, which is exactly what the break-even ROAS section below walks through.
CPA vs. CPL — know which one you’re quoting
CPL should only ever refer to a raw lead (form fill, call, chat). CPA should refer to an actual acquired customer or closed sale. Using them interchangeably in reporting is one of the fastest ways to make an account look healthier than it is — a $30 CPL sounds great until you realise the sales team is closing one in every twenty.

Return on Ad Spend (ROAS)
ROAS is the most quoted PPC metric in the industry, and the most frequently misunderstood, because it measures revenue — not profit. A campaign can post an impressive ROAS and still lose the business money once cost of goods, shipping, returns and overheads are factored in.
The formula
ROAS = Revenue Generated ÷ Ad Spend
It’s commonly expressed as a multiple (3.0x) or a percentage (300%) — both mean the same thing.
Worked example
Sample Co’s 75 conversions generated $18,750 in revenue (an average order value of $250) against $6,250 in spend.
ROAS = $18,750 ÷ $6,250 = 3.0x, or 300%
Why ROAS alone can lie to you
A 300% ROAS sounds like a resounding win. But if Sample Co runs on a 20% gross margin, that $18,750 in revenue only carries $3,750 in gross profit — which doesn’t cover the $6,250 spent to generate it. The campaign would be losing money at a ROAS most marketers would call excellent. This is the single most common reporting failure we see when we audit incoming accounts: ROAS presented as the finish line, when it’s actually just an input to the number that matters, which is true ROI.
True ROI (Accounting for Margin)
True ROI answers the only question that matters to the business owner: after this campaign spent money, did the business end up with more money than it started with?
The formula
Gross Profit = Revenue × Gross Margin
ROI = ((Gross Profit – Ad Spend) ÷ Ad Spend) × 100
Worked example
Using Sample Co’s numbers with a realistic 40% gross margin (rather than the 20% doomsday scenario above):
Gross Profit = $18,750 × 0.40 = $7,500
ROI = (($7,500 – $6,250) ÷ $6,250) × 100 = 20%
Notice the gap: a 300% ROAS becomes a 20% ROI once margin enters the picture. Neither number is wrong — they’re answering different questions. ROAS tells you how efficiently you turned spend into revenue. ROI tells you how efficiently you turned spend into profit. Report both, always, and never let ROAS stand in as a proxy for profitability in front of a client or a CFO. We cover how to build that kind of report — the one a CFO will actually read — in our Google Ads reporting guide.
Where margin figures actually come from
This is the step most PPC reporting skips, because the agency running the ads usually doesn’t have access to the client’s cost of goods sold, fulfilment costs, payment processing fees or return rates. If you’re managing your own campaigns, pull a blended gross margin figure from finance before you calculate ROI — and if you’re a business handing this off to an agency, that margin figure is the single most valuable input you can hand over on day one.
Break-Even ROAS
Break-even ROAS flips the ROI formula around to answer a more useful operational question: what ROAS do we need to hit before we start actually making money? Once you know this number, you can look at a campaign’s ROAS in Google Ads and immediately know if it’s profitable — no spreadsheet required.
The formula
Break-Even ROAS = 1 ÷ Gross Margin (expressed as a decimal)
Worked example
At Sample Co’s 40% gross margin:
Break-Even ROAS = 1 ÷ 0.40 = 2.5x
Any ROAS above 2.5x is profitable; anything below it is losing money on every dollar spent, no matter how good the campaign looks in the platform’s dashboard. Sample Co’s actual 3.0x ROAS sits comfortably above the 2.5x break-even line — which is a more honest way to read the account’s performance than the ROI percentage or the raw ROAS number in isolation.
Why this number belongs on every dashboard
Break-even ROAS turns a lagging, after-the-fact calculation (ROI) into a live benchmark you can check daily inside the ad platform. Set it as a target ROAS in Smart Bidding once you trust the number, and you’ve automated the boundary between profitable and unprofitable spend directly into the bidding algorithm. Recalculate it whenever margin shifts — a sale, a supplier price increase, a shipping cost change all move this number, and a stale break-even ROAS is worse than none at all because it gives false confidence.
Customer Acquisition Cost (CAC)
CAC is frequently confused with CPA, but it should be a bigger, more honest number. CPA usually only reflects media spend. CAC should reflect everything it costs to acquire a customer — media spend, agency or management fees, tools, and a fair share of the team’s time.
The formula
CAC = (Total Sales & Marketing Spend) ÷ (Number of New Customers Acquired)
Worked example
Sample Co spent $6,250 on media plus a $1,500 monthly management fee, and acquired 75 leads that converted at a 40% close rate — 30 actual customers.
CAC = ($6,250 + $1,500) ÷ 30 = $258.33
Compare that to the CPA calculated earlier ($83.33 per lead) and the gap is stark — because CPA measured cost per lead, while CAC measures the fully-loaded cost per paying customer. Businesses that only ever look at CPA consistently underestimate what it actually costs them to grow, which is exactly why CAC is the number that belongs in front of a board or an investor, not CPA or ROAS.
LTV:CAC Ratio
Customer Acquisition Cost only means something in relation to what that customer is worth over the time they stay with the business. That’s Lifetime Value (LTV), and the ratio between the two is one of the clearest single indicators of whether a growth channel is sustainable.
The formulas
LTV (gross profit basis) = Average Order Value × Purchase Frequency × Customer Lifespan × Gross Margin
LTV:CAC Ratio = LTV ÷ CAC
Worked example
Sample Co’s customers buy an average of 3 times over a 2-year relationship, at a $250 average order value and 40% gross margin.
LTV = $250 × 3 × 0.40 = $300 (gross profit per customer)
LTV:CAC = $300 ÷ $258.33 ≈ 1.16:1
That ratio is a warning sign. The commonly cited healthy benchmark for LTV:CAC is around 3:1 — enough headroom to cover the cost of acquisition, absorb churn, and still fund the rest of the business. At 1.16:1, Sample Co is barely covering what it costs to win the customer in the first place, even though the campaign’s ROAS and ROI both looked positive earlier in this guide. This is the value of calculating every metric in this article rather than stopping at the first one that looks good — a profitable-looking campaign can still be funding an unsustainable business if the customer doesn’t stick around long enough or come back often enough.
Use revenue LTV or profit LTV — but say which
Some businesses calculate LTV on revenue rather than gross profit, which produces a much larger, more flattering number. Neither approach is wrong, but they are not interchangeable, and comparing your LTV:CAC ratio against an industry benchmark calculated the other way will mislead you. We use gross-profit-basis LTV by default because it’s the version that actually tells you whether a channel is sustainable — revenue LTV tells you about scale, not profitability.

Statistical Significance Basics for A/B Testing
Every PPC platform lets you run two ad variations, wait a few days, and declare a winner. Most of those “winners” are noise. Without a basic statistical significance check, you will regularly kill an ad that was actually performing fine, or scale one that got lucky.
The simplified formula
For comparing two conversion rates, calculate the standard error of the difference, then the z-score:
SE = √( p₁(1-p₁)/n₁ + p₂(1-p₂)/n₂ )
z = (p₂ – p₁) ÷ SE
Where p₁ and p₂ are the conversion rates of variant A and B, and n₁ and n₂ are the number of clicks each variant received. A z-score above 1.96 generally indicates the difference is significant at a 95% confidence level.
Worked example
Ad A: 1,000 clicks, 50 conversions — a 5% conversion rate.
Ad B: 1,000 clicks, 65 conversions — a 6.5% conversion rate.
SE = √( (0.05 × 0.95 ÷ 1,000) + (0.065 × 0.935 ÷ 1,000) ) = √(0.0000475 + 0.0000608) = √0.0001083 ≈ 0.0104
z = (0.065 – 0.05) ÷ 0.0104 ≈ 1.44
A z-score of 1.44 falls short of the 1.96 threshold for 95% confidence. Ad B looks 30% better in relative terms — a result most accounts would call a winner and act on immediately — but statistically, this test hasn’t yet proven anything. The honest read is “promising, keep running it,” not “B wins, pause A.”
Practical rules of thumb
- Don’t call a test before each variant has at least 100 conversions — below that, sample size alone makes most results unreliable regardless of the z-score.
- Let tests run through at least one full weekly cycle, since day-of-week behaviour skews conversion rate on their own.
- A test that looks flat after a genuinely large sample is still a useful result — it tells you the variable you tested doesn’t matter as much as you assumed, which redirects testing effort somewhere more productive.
- Treat any “95% confidence” badge inside a platform’s native reporting as a starting point, not gospel — recalculate manually for any decision with real budget riding on it.
Working backwards: how much sample size do you need?
If you’d rather plan a test than analyse one after the fact, a simplified minimum sample size per variant is:
n ≈ 16 × p(1-p) ÷ (minimum detectable effect)²
Where p is your baseline conversion rate and the minimum detectable effect is the smallest absolute lift you actually care about catching. For Sample Co’s 5% baseline and a target of reliably detecting a 1.5-point lift (to 6.5%): n ≈ 16 × 0.05 × 0.95 ÷ 0.015² ≈ 3,378 clicks per variant. That’s a useful reality check before launching a test — it tells you upfront whether your account even gets enough traffic to reach a trustworthy answer within a reasonable timeframe, rather than finding out four weeks in.
Building a Simple Model to Sanity-Check Campaign Profitability
You don’t need a data analyst or a BI dashboard to know whether a campaign is working. A five-line spreadsheet, rebuilt from the formulas above, will catch most problems before they become expensive. Here’s the model, using Sample Co’s numbers end to end.
- Spend: $6,250
- Clicks: 1,250 (CPC: $5.00)
- Conversions (leads): 75 (Conversion rate: 6%, CPA: $83.33)
- Close rate: 40% → 30 customers
- Average order value: $250 → Revenue: $18,750 (ROAS: 3.0x)
- Gross margin: 40% → Gross profit: $7,500 (ROI: 20%, break-even ROAS: 2.5x)
- Fully-loaded CAC (incl. $1,500 fee): $258.33
- LTV (gross profit basis): $300 (LTV:CAC: 1.16:1)
Reading down that list top to bottom is exactly how you should audit any campaign: each line either confirms or contradicts the story the line above it told. In Sample Co’s case, ROAS and ROI both say the campaign is profitable this month — but the LTV:CAC ratio says the underlying growth model needs work, because the business isn’t retaining or repeat-purchasing enough to comfortably cover what it costs to win each customer.
Stress-testing the model
The real value of a simple model is running it through a change before that change happens in the real account. If Sample Co’s CPC rose 20% to $6.00 with clicks and conversion rate held flat, spend would climb to $7,500, CPA would rise to $100, and ROAS would fall to 2.5x — precisely the break-even line calculated earlier. That’s a genuinely useful early-warning number: it tells you exactly how much headroom the account has before a CPC increase (from rising competition, seasonality, or an algorithm change) turns a profitable campaign into a break-even one.
Common Calculation Mistakes
- Reporting ROAS as if it were ROI. They measure different things — revenue efficiency versus profit efficiency — and conflating them is the single most common error in PPC reporting.
- Using platform-attributed conversions as revenue without checking for duplicates. Cross-device and cross-channel attribution regularly counts the same sale more than once across Google Ads, Meta and GA4.
- Calculating CAC using only media spend. Leaving out management fees, tools and staff time understates what growth actually costs and skews every ratio downstream of it.
- Applying a single blended gross margin to every product or service line. A business selling both a 15% margin item and a 60% margin item needs break-even ROAS calculated separately for each — a blended figure will misprice both.
- Declaring an A/B test winner on relative lift alone. A 30% relative improvement in conversion rate means nothing if the underlying sample size can’t support statistical confidence, as shown in the worked example above.
- Comparing LTV:CAC ratios across businesses that calculate LTV differently. Revenue-basis and profit-basis LTV produce very different numbers from identical underlying data.
- Ignoring returns, refunds and chargebacks in the revenue figure. Gross revenue at time of sale is not the same as revenue that actually stays in the business, particularly in ecommerce categories with high return rates.
- Letting a stale break-even ROAS sit in a Target ROAS bid strategy. Margins move with sales, pricing changes and supplier costs — a break-even ROAS calculated six months ago can quietly be steering spend in the wrong direction.
Frequently Asked Questions
What’s the difference between ROAS and ROI in PPC?
ROAS measures revenue generated per dollar of ad spend (Revenue ÷ Spend). ROI measures actual profit generated once cost of goods and margin are accounted for (((Revenue × Margin) – Spend) ÷ Spend). A campaign can show a strong ROAS and still be unprofitable once true margin is applied — which is why both numbers, not just one, belong in any serious performance report.
What ROAS should I be aiming for?
There’s no universal target — it depends entirely on your gross margin. Calculate your break-even ROAS first (1 ÷ gross margin as a decimal), then treat any ROAS above that line as genuinely profitable. A 4x ROAS can be barely break-even for a low-margin business and hugely profitable for a high-margin one.
How is CAC different from CPA?
CPA is typically media spend divided by conversions (often leads). CAC should be the fully-loaded cost — media spend plus agency or management fees, tools and relevant staff time — divided by actual paying customers acquired. CAC is almost always a meaningfully bigger number than CPA, and it’s the one that matters for board-level or investor reporting.
How many conversions do I need before an A/B test result is trustworthy?
As a practical minimum, aim for at least 100 conversions per variant before drawing conclusions, and run the test through at least one full week to average out day-of-week effects. Below that, calculate a z-score before acting — a result that looks like a clear winner can still fall well short of statistical significance, as shown in the worked example in this guide.
Should I use revenue or gross profit to calculate LTV?
Gross profit is the more rigorous choice, because it reflects what the business actually keeps from each customer relationship, not just how much revenue passed through. Revenue-basis LTV produces a larger, more flattering number and is useful for understanding scale — but don’t use it to judge whether a growth channel is sustainable, and never compare it directly against a benchmark calculated on gross profit.
Why do my Google Ads dashboard numbers not match my finance team’s numbers?
Google Ads reports platform-attributed conversions and revenue, which don’t account for returns, refunds, cross-channel duplicate attribution, or the difference between gross revenue and gross profit. Treat the platform dashboard as a directional, real-time view of media performance, and reconcile against finance-reported numbers monthly for the figures that actually determine profitability — true ROI, CAC and LTV:CAC in particular.
Where to Start
You don’t need to calculate all ten of these metrics before your next campaign review. Start with three: your actual gross margin (ask finance, don’t estimate it), your break-even ROAS derived from that margin, and your fully-loaded CAC. Those three numbers alone will tell you more about whether your PPC spend is genuinely working than a dashboard full of ROAS and conversion rate ever will.
If you’d rather have someone build and maintain this model against your live account — margin data, break-even targets, CAC and LTV:CAC tracked properly, not guessed at — that’s exactly the kind of Google Ads management we do, and our Google Ads pricing page shows what it costs. Get in touch and we’ll walk through your numbers with you.

Keep reading
Related posts
Google Ads Reporting: How to Build Reports That Actually Show What’s Working (2026)
A practical guide to building a Google Ads reporting framework and dashboard that shows business owners, marketers and boards what's actually working.
How to Maximise Google Ads ROI: A Complete Guide for Australian Businesses (2026)
A practical, no-fluff guide to maximising Google Ads ROI in Australia — conversion tracking, account structure, Smart Bidding, ad copy, landing pages,…
Got a project you'd like to talk through?
Tell us what you're working on — we'll come back with a plan.